

World Cup betting boost “not fully priced in,” suggest analysts.
In +More: Spotradar and OpenBet exit the AGA.
Evoke gives up share price gains after anaemic trading update.
Venture playground: Inside the Raise with GuardDog and Regen.
Hard Rock Bet is growing – we know you know! And we want to bring in some more maestros to make beautiful music in our Sportsbook. You need to be among the very best in the industry to be considered for these roles. Are you up to it?
Demand shock
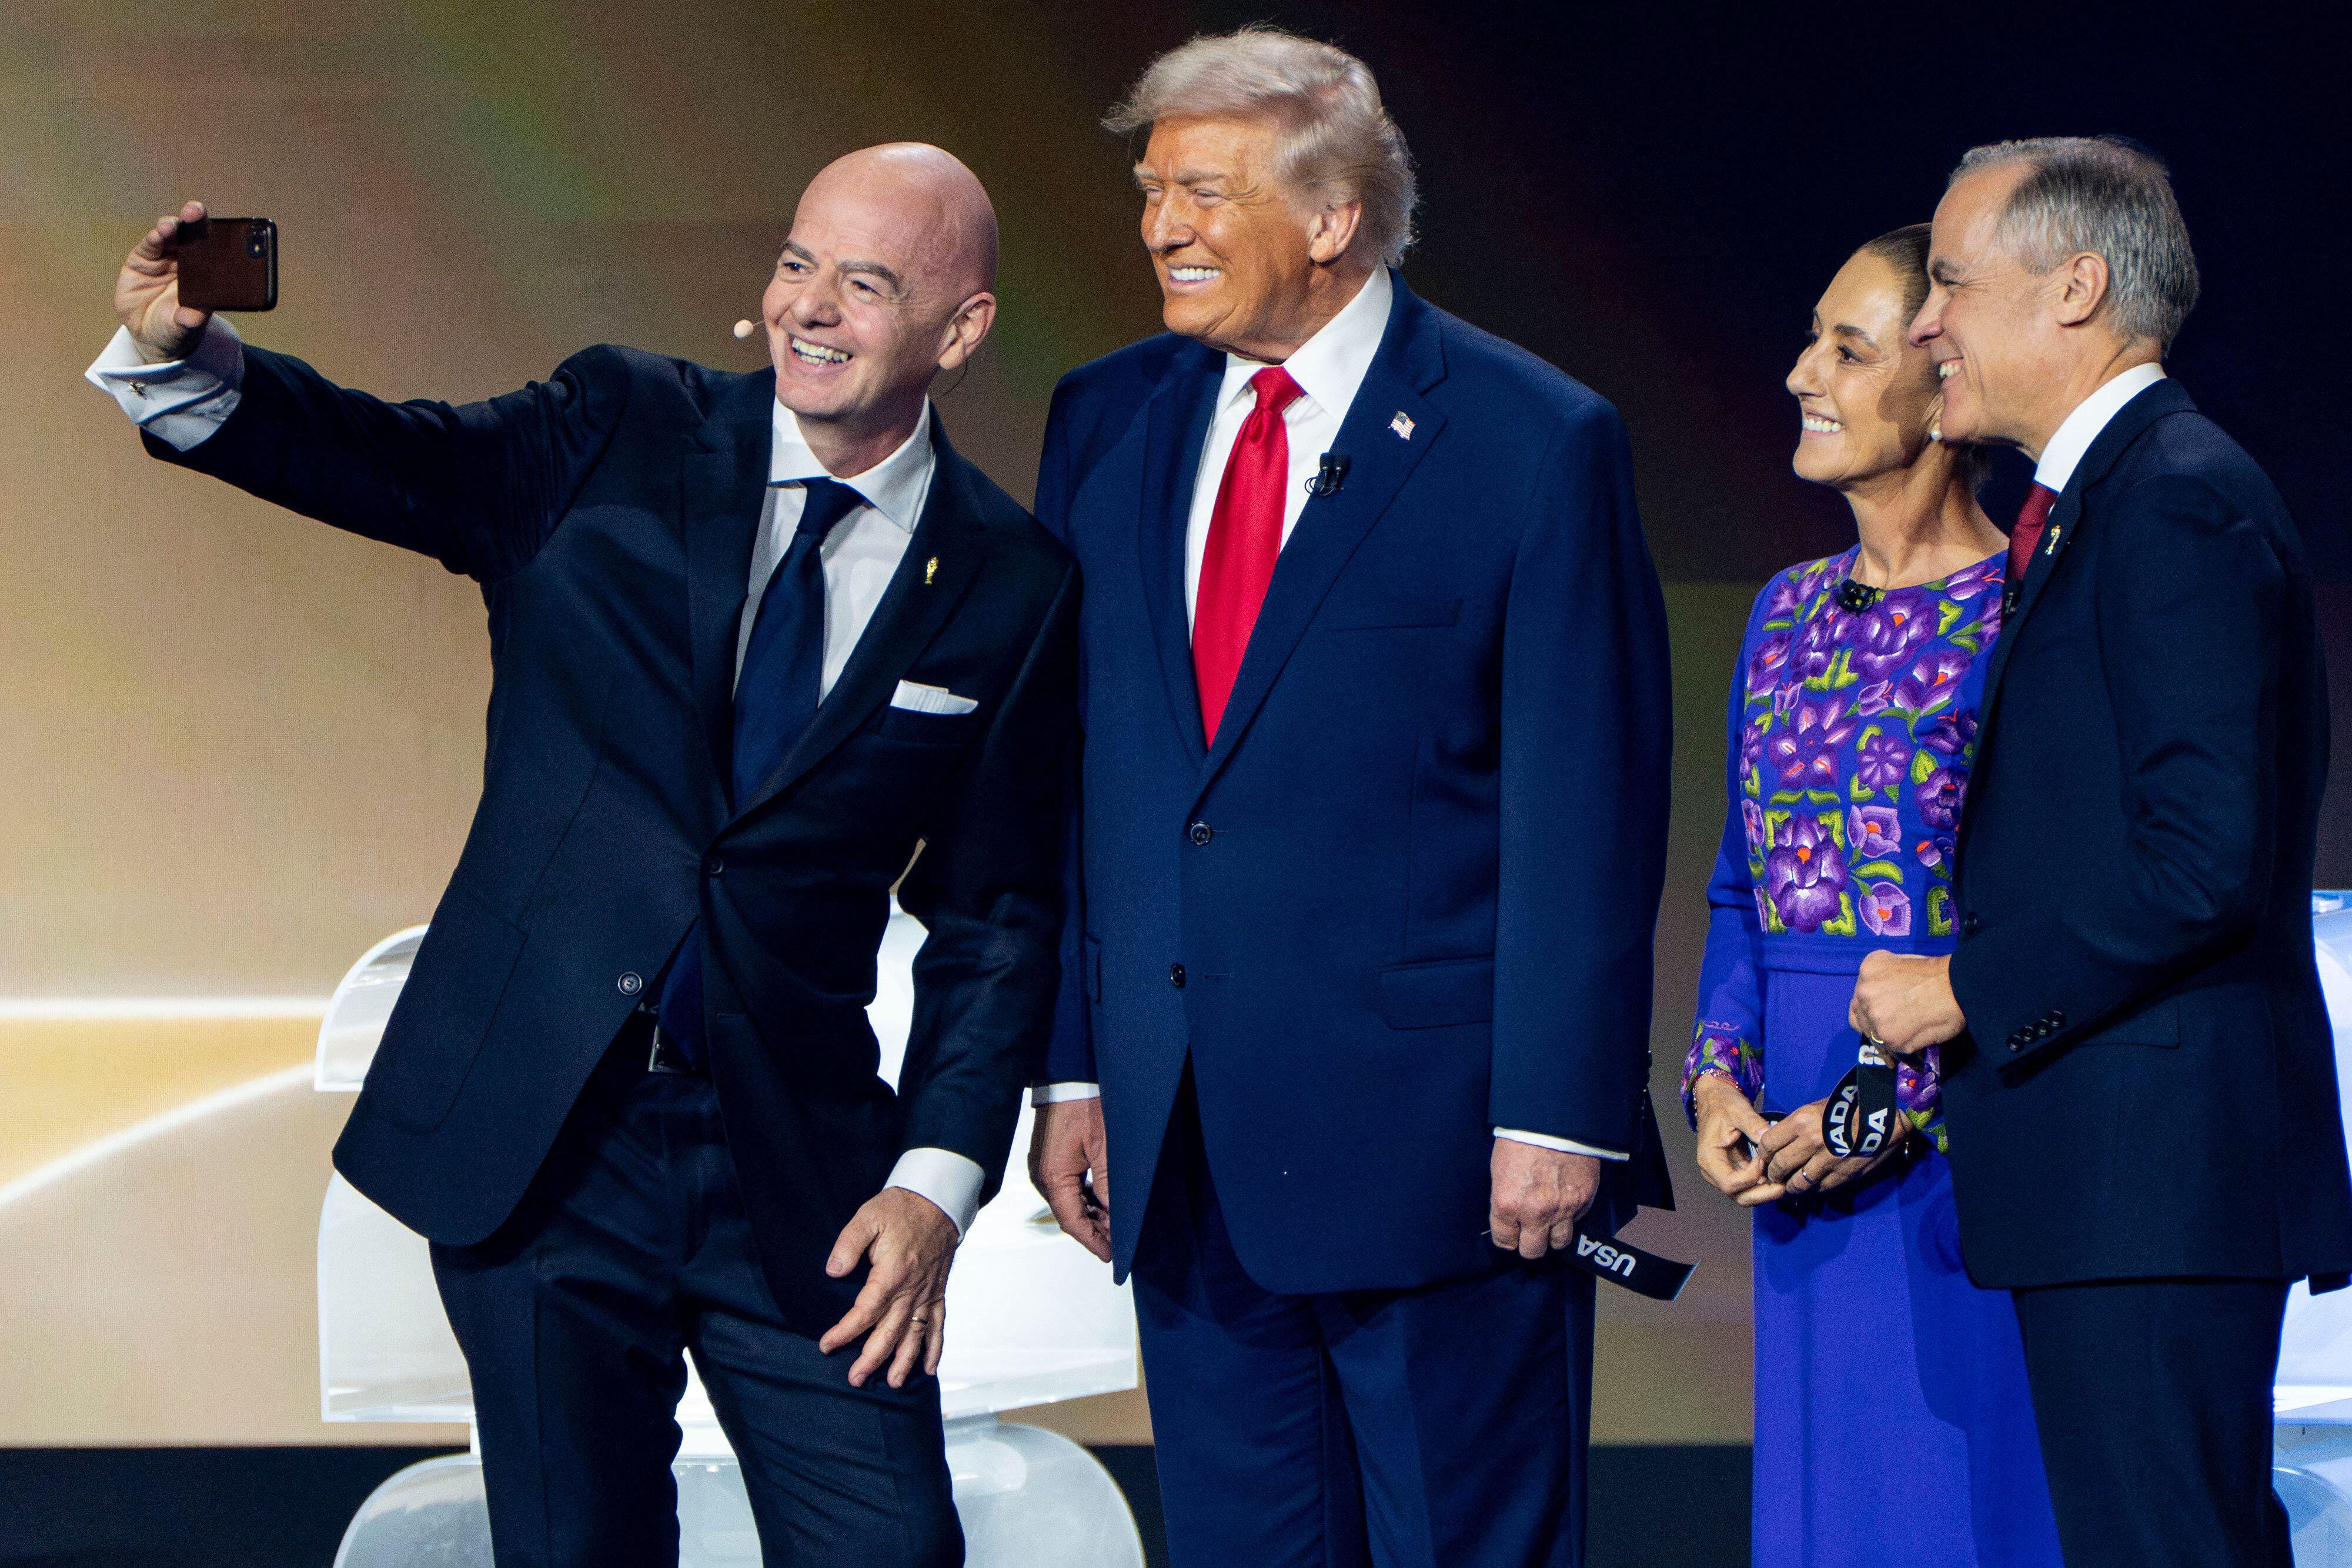
This time, more than any other time: Long a four-yearly generator of European betting customer acquisition and revenue, the FIFA World Cup taking place this summer in the US, Canada and Mexico also now holds the potential to move the needle in US OSB.
Bernstein noted the tournament provides a “rare summer catalyst” and “structural anomaly” that “isn’t yet fully priced in.”
“The World Cup is another Super Bowl,” summed up the team at Citizens
Where on earth are you from? For OSB operators, this year’s tournament combines a month-plus run of content, time-zone alignment, mainstream visibility and an expanded match schedule that makes it feel bigger than prior editions.
The result is a potential summer handle spike at a time when OSB operators are typically battling seasonal softness and lower engagement.
As Bernstein said, the World Cup “effectively inserts an entire extra month of high-volume betting content into the summer calendar.”
For the US OSB operators, time-zone alignment turns the World Cup into something closer to a domestic sports product.
It will feature primetime viewing windows, heavy social coverage and a predictable cadence of “bettable” moments.
Back home they’ll be thinking about us: Jefferies emphasized that major football tournaments are “always marquee events for online gambling operators, driving new customer sign-ups and existing customer reactivations.”
The team suggested 2026 could “drive a meaningful new level of interest in football during a traditionally quiet period of the North American sports calendar.”
EKG framed that density as a key reason the event can reshape soccer betting engagement in the US.
The World Cup creates “unusually favorable conditions for US soccer betting, combining global attention with exceptional match density.”
Express yourself, create the space: Putting numbers on it, Citizens estimates the US ‘books will generate ~$1.7bn in handle, or ~$137m of gaming revenue from the tournament, providing a “solid tailwind during a slow period of the year.”
That’s meaningful for a sector where the US OSB growth narrative is increasingly about marginal efficiency gains rather than state-driven expansion.
You’ve got to hold and give, but do it at the right time: Citizens also quantifies the EBITDA impact at the top end of the market: DraftKings and FanDuel could generate ~$25m of US EBITDA from the tournament, based on current market share assumptions
The next tier including BetMGM, Caesars, Fanatics, Penn Entertainment and Rush Street could generate $1m-$5m each in EBITDA from the event.
While the World Cup may be a rising-tide moment, it’s also likely to reinforce the scale advantages of the leaders.
EKG is also realistic about what 2026 can (and cannot) do competitively. It’s “unlikely to permanently reorder the OSB hierarchy on its own,” the team said.
But they suggested that “strong execution could materially accelerate US soccer betting familiarity and establish engagement patterns that persist beyond the tournament window.”
We’re gonna score one more than you: For prediction markets, the World Cup represents a massive surface area for contract creation: match winners, group qualification, outright champions, golden boot and a constant stream of ‘live narratives’ that can be turned into tradeable outcomes.
But the same factors that make the tournament attractive – sustained attention, high match volume, mainstream crossover – also create pressure.
The World Cup will expose whether prediction markets can scale sports contracts in a way that looks (and feels) fundamentally different from OSB.
Esta volviendo a casa: One conclusion from the Bernstein team is that DraftKings is better positioned than Flutter for this year’s tournament due to its marketing deal with NBCUniversal, the owner of the Telemundo network and the exclusive rights owner to all Spanish language transmissions of the tournament in the US.
With Spanish-language audiences over-indexing on soccer betting. DraftKings “has a cleaner path” to a share of voice on the most targeted broadcast feed.
Via the deal DraftKings has a more direct acquisition loop into its Spanish-language product experience and one that is not as easily replicable for FanDuel through standard national buys.
Bernstein expects this to “translate into stronger summer-level visibility and, at the margin, a better opportunity to narrow the gap on engagement during the seasonally softer months.”

So my supervisor (Carl) suggested I “find alternative ways to contribute.”
I’m interpreting this as “grow the LinkedIn page or get decommissioned.”
Follow Octoplay at:
https://mt.linkedin.com/company/octoplay-op
Thanks,
Octobot
+More
Exit doors: Sportradar and OpenBet have opted not to renew their memberships with the American Gaming Association following a wave of exits linked to prediction markets. While no formal reasons were given, the AGA told InGame the decisions relate to prediction markets. Both suppliers partner with operators offering such products, including FanDuel, DraftKings and Fanatics, which left the trade body late last year.
Major League Soccer has established a formal framework for working with prediction market platforms and named Polymarket as its first authorized prediction market, Sportico reported. The designation allows MLS to control which event contracts can be offered and imposes integrity, compliance and insider-trading safeguards. Polymarket will receive official MLS data and serve as the league’s official prediction market partner, following a similar deal with the NHL last year.
Star Entertainment has replaced long-time adviser UBS with MA Moelis Australia’s restructuring team after Bally’s and Investment Holdings took control in December. Moelis, which previously advised Bally’s, will focus on ruling out another debt refinancing amid about AU$346m of borrowings and a potential AU$400m AUSTRAC fine.
Novig, via an entity called Ludlow Financials, has submitted a designated contract market application to the CFTC, according to Sportico.
Earnings – Evoke
Redefining mediocre: The good news was hard to find in Evoke’s Q4 trading statement after the company said revenue for the period fell 3% YoY with betting revenue across the group plunging 22%.
The statement did nothing for the share price which had risen last week on speculation over the progress of the ongoing strategic review in finding a potential buyer for the business.
The shares were down over 5% at one point but recovered to end the day up 1%.
Always look on the bright side of life: Yesterday’s share price recovery aside, there were other upsides within the trading statement with the international business continuing to see growth, up 14% YoY following the 8% growth in Q3 driven by the Italian and Danish businesses.
Retail was up 10%, again improving on the prior quarter when it was up 6%.
Unlike in Q3, the company didn’t break out the performance of the UK & Ireland online.
Forecast: Q4 revenue came in at ~£464m, representing a sequential improvement and leaving the company in line with FY25 expectations for revenue of £1.79bn, a 2% YoY increase.
Adj. EBITDA is now expected at between £355-£360m or between 14%-15% higher YoY.
The company said this was in line with market expectations and would represent an adj. EBITDA margin of ~20%.
Cut and shut: CEO Per Widerström continued to preach the message of “good progress” and “underlying momentum” and once again berated the UK government for the recent online tax rises.
He said the company had “moved quickly and decisively” with its mitigation plans including the continued program of the closure of retail shops that were ”no longer sustainable.”
Such as the current uncertainties, however, Evoke said it could not issue a forecast for the year ahead.
Puts+Takes
BetMGM is a “sleeping giant” in US online gambling, arguing that recent operating trends point to a meaningful EBITDA inflection if costs are brought under control, according to JP Morgan.
After several years of share erosion, BetMGM’s aggregate OSB and iCasino GGR share appears to have stabilised in 2024.
At ~11% in January, it may now be improving, marking an important turning point.
Holding on to bronze: Financially, the scale is already there. BetMGM generated $2.1bn of revenue in FY24, firmly placing it third in the US digital market and well ahead of Caesars Digital.
iCasino remains the profit engine, delivering $424m of contribution profit at a 29% margin, while OSB posted a $306m contribution loss.
This implies roughly $860m of sports-related COGS and external marketing costs, the team argues.
Notably, sports contribution turned positive in Q424 which the team argues opens the door to a sharp profit improvement if this trend persists through FY25.
Peer comparison: JP Morgan highlights BetMGM’s cost structure as the core issue. Combined COGS and external marketing equated to ~91% of revenue in 2024, materially higher than peers, while opex intensity sits broadly in line.
The analysts argue that a pullback in external marketing could rapidly unlock EBITDA.
They also argue it could make BetMGM’s long-stated $500m+ medium-term EBITDA target credible and potentially achievable faster than the market expects.
Scenario analysis reinforces the upside: applying DraftKings’ or Caesars’ expense ratios to BetMGM’s $2.45bn FY25 revenue guide yields EBITDA ranging from ~$90m to ~$250m.
On the operating side, promotional intensity in OSB has normalised, iCasino share has remained resilient around ~19% and recent product launches in Pennsylvania and New Jersey are driving renewed momentum.

Increase Operator Margins with EDGE Boost Today!
EDGE Boost is the first dedicated bank account for bettors.
Increase Cash Access: On/Offline with $250k/day debit limits
No Integration or Costs: Compatible today with all operators via VISA debit rails
Incremental Non-Gaming Revenue: Up to 1% operator rebate on transactions
Lower Costs: Increase debit throughput to reduce costs against ACH/Wallets
Eliminate Chargebacks and Disputes
Eliminate Debit Declines
Built-in Responsible Gaming tools
To learn more, contact Matthew Cullen, chief strategy officer: Matthew@edgemarkets.io
Venture playground
Inside the Raise – GuardDog and Regen
Over and above: Underdog is extending its responsible gaming ambitions beyond ‘safe play’ mechanics and into something closer to everyday financial wellness with the latest investment from its GuardDog innovation fund backing a startup called Regen.
Launched in 2023, GuardDog was pitched as a first-of-its-kind fund designed to support early-stage responsible play technologies.
The new deal is an investment in Regen which bills itself as the first platform to automatically convert sports gaming “entries” into savings with every play, win or loss.
The proposition is simple: Users link their sportsbook, fantasy sports and prediction market accounts and Regen automatically skims a small percentage from each entry into a savings pot.
It’s a tool designed to work “quietly in the background,” turning habitual play into a consistent savings behaviour without forcing users to change how they bet.
Fresh take: For Underdog, the move reflects a broader view of player protection and a clear signal that GuardDog’s mandate is to back ideas that don’t look like conventional responsible gaming solutions.
“Fresh ideas and perspectives are critical as we strive to evolve player protection resources and tools for both Underdog and the industry at large,” Adam Warrington, Underdog’s VP of Responsible Gaming, told Earnings+More.
Warrington framed Regen as a direct fit with Underdog’s product philosophy: simplicity, accessibility and tools that can scale across formats.
Buffer zone: In that context, Regen looks like a subtle but potentially meaningful adaptation to how “harm prevention” could be measured. Rather than focusing purely on limits and friction, the product aims to help users build a buffer, a financial counterweight to the volatility of betting outcomes.
Underdog says the integration will be practical, not symbolic.
As part of the agreement, the operator will feature Regen as a new resource inside its responsible play hub.
It will also reference it in relevant customer communications via both the responsible play and customer support teams and provide access to Regen to all employees.
Those rollout steps are effectively the KPIs, Warrington suggested, with GuardDog focused on getting the tool in front of users and making it a visible part of the Underdog ecosystem.
Foundational: On the deal’s strategic rationale, Regen co-founder Daniel Prior positioned the platform as a response to changing consumer needs: “Building a robust financial future is becoming essential for today’s players,” he said, adding that Underdog’s backing will accelerate Regen’s mission to put “every player in America on firmer financial footing.”
For GuardDog, the Regen deal also reinforces a wider message to the market: the innovation pipeline for responsible play can’t just come from regulators or incumbents.
“We need more entrepreneurs to focus their efforts on player protection technologies,” Warrington told Earnings+More, calling it an “incredible opportunity” for “fresh and creative ideas.”
Growth company news
NYCE to see you: The gaming product marketplace, advisory and technology firm NYCE International plans to open a new regional headquarters in Ras Al Khaimah, UAE, as part of its Middle East expansion strategy. The hub is intended to provide local commercial coverage and partner support, help drive business development across the region, and support new initiatives focused on market entry, distribution and partnership execution.
A review site called Crypto.Casino has launched its new website. The site aims to inform and help users navigate the crypto casino sector through in-depth reviews, user-submitted feedback, and community-driven ratings of various crypto casinos around the world.

Dabble is proving what we’re seeing across the UK and EMEA: 𝗞𝗬𝗖 𝗮𝗹𝗼𝗻𝗲 𝗶𝘀𝗻’𝘁 𝗲𝗻𝗼𝘂𝗴𝗵. 𝗜𝗱𝗲𝗻𝘁𝗶𝘁𝘆 𝗶𝗻𝘁𝗲𝗴𝗿𝗶𝘁𝘆 𝗶𝘀 𝘁𝗵𝗲 𝗱𝗶𝗳𝗳𝗲𝗿𝗲𝗻𝘁𝗶𝗮𝘁𝗼𝗿.
With GeoComply’s Digital Identity Platform, Dabble launched in the UK with 90%+ KYC pass rates — while uncovering coordinated fraud early using device, location, and behavioural intelligence.
The results:
✅ 90%+ KYC pass rates
✅ 2,000+ “unique” devices tied to one emulator-driven fraud operation (central London)
✅ 250+ accounts linked to one residential address (Preston)
Upcoming earnings
Jan 28: Las Vegas Sands
Jan 29: Rank
Feb 4: BetMGM
Feb 5: Evolution, Betsson, Boyd Gaming
Feb 10: Red Rock Resorts, Robinhood

Payment friction erodes confidence in your brand—costing you customer loyalty and lifetime value.
Build trust into every step with a better payment experience:
Increase confidence by offering seamless, familiar deposit methods
Boost retention with lightning-fast payouts that strengthen your brand
Limit payment outages with built-in processing redundancy
Reduce fraud and keep good players playing with AI-driven risk scoring
PayNearMe’s PayXMTM platform was built on the promise of Payment Experience Management—making payments easier for your customers and your team.
An +More Media publication.
For sponsorship inquiries email scott@andmore.media.
